
Navigating Family Business Succession: The Ethics of Unequal Inheritance
Key Takeaways
- Succession planning often requires prioritizing business continuity over equal inheritance.
- Only 30% of family businesses survive the transition to the second generation.
- Financial experts recommend using liquid assets to balance estates rather than splitting company equity.
The dilemma of succession planning in family-owned enterprises often pits the desire for operational continuity against the principles of equal inheritance. A 64-year-old business owner recently sought guidance on whether allocating 70% of their company to the son actively involved in the business is ethically sound, particularly when the other son remains uninvolved. This scenario highlights the complex intersection of professional meritocracy and parental obligation, forcing owners to weigh the long-term stability of the firm against potential familial resentment.
Financial advisors and estate planners frequently emphasize that 'fair' does not always mean 'equal.' In this case, the owner expressed specific concerns regarding the long-term stability of the uninvolved son’s marriage, fearing that a larger inheritance could be jeopardized by external legal factors. Experts suggest that if the active son is the primary driver of the company’s value, rewarding his contribution with a majority stake is a standard business practice designed to prevent future management gridlock and ensure the company’s survival.
Historically, family businesses that fail to clearly define succession roles often face significant decline during generational transitions. Statistics indicate that only about 30% of family-owned businesses successfully transition into the second generation, with that number dropping to 12% for the third. By prioritizing the active heir, the owner is attempting to mitigate the risk of a 'passive' shareholder exerting undue influence or demanding dividends that could stifle reinvestment and growth.
Looking ahead, the owner must balance these professional decisions with transparent communication to avoid permanent family estrangement. Experts recommend utilizing buy-sell agreements or life insurance policies to provide the non-active child with liquid assets, thereby balancing the total estate value without compromising the company’s equity structure. Ultimately, the goal is to protect the business as a viable entity while ensuring that the inheritance strategy reflects both the sweat equity invested by the active son and the parent’s desire for equitable treatment of all heirs.
Subscribe to the Global Briefing
Receive our flagship executive dispatch every morning. Essential geopolitical analysis, financial benchmarks, and breaking world events delivered to your inbox.
Related Stories & Follow-ups
Editorial Wire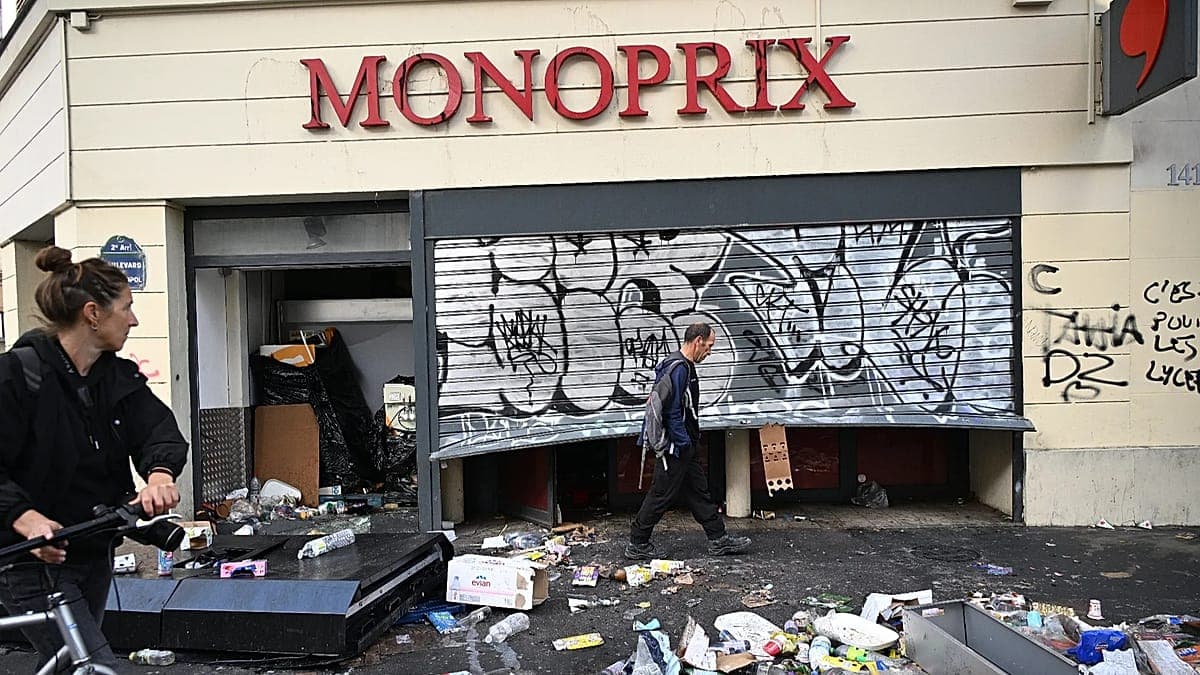 Business & Economy
French Businesses Face Massive Recovery Costs Following Widespread Looting and Civil Unrest
Brent Crude Hits Five-Month High Amid Escalating Middle East Tensions
Saudi Aramco Facilities Targeted in Suspected Houthi Drone Strike
Reader Discussion
Leave a Comment
0 Comments
Owner
Editorial Oversight & Machine-Assisted Reporting
Human-in-the-Loop VerifiedEditorial Oversight & Machine-Assisted Reporting: This dispatch was synthesized and localized via OPA automated intelligence under continuous human editorial supervision.
Wire Source
This report was synthesized from MarketWatch under journalistic fair use.